Buy Now Pay Later Options for Furniture: How to Choose


The sofa fits the room, the fabric feels right, and the smaller payment at checkout looks manageable. Then rent comes due, utilities clear the bank account, and an installment for another purchase lands before payday. The furniture may offer comfortable support, but the financing needs to fit the household just as carefully.
Choosing among buy now pay later options starts with a repayment calendar, not an approval limit. For homeowners and renters furnishing a welcoming home, the right choice leaves room for everyday bills, emergency savings, and the full cost of the purchase.
Buy Now Pay Later Options at a Glance
Buy now, pay later options by structure
| Option | How payment is split | Typical interest | Typical term | Best for |
|---|---|---|---|---|
| Pay-in-four | Four scheduled payments | Often zero interest; fees may apply | About six weeks; confirm the agreement | Accent pieces and ready-to-deliver items |
| Longer installment plan | Fixed monthly payments | Interest may apply under the offer | Several months, as specified in the agreement | Sectionals, sleeper sofas and dining sets |
| Promotional or deferred-interest store financing | Monthly payments during the promotion | Deferred interest may be charged back if the balance isn't cleared in time | Set by the offer | Shoppers who can clear the full balance in the window |
| Conventional financing or store credit | Fixed or revolving payments | Set by the agreement | Fixed loan term or revolving account schedule | Large or ongoing purchases with a clear repayment plan |
Buy now, pay later is short-term financing, although checkout menus may also present longer-term alternatives. The structure determines how quickly the balance must be repaid and which costs deserve attention.
In 2023, 9.3% of U.S. consumers used a buy now, pay later service, up from 6.6% in 2021, according to the Federal Reserve Bank of Boston. It's a familiar payment choice, but familiarity doesn't make every agreement interchangeable.
Understand the Financing Structure
Pay-in-four is a short ladder: fewer steps, closer together. A longer installment plan is a staircase: smaller steps may feel easier, but interest can increase the total paid.
Deferred interest is a deadline. Unlike a true no-interest offer, a deferred-interest promotion can create interest charges reaching back to the purchase if its conditions aren't met. Conventional financing is a measured path governed by the signed agreement, with either a fixed payoff schedule or revolving payments.
Lott's Furniture offers Shop Now, Pay Later and extended financing, with Financing and More Ways to Pay listed on its site. Specific availability and terms should be confirmed before treating any category in the table as an available offer.
Shoppers across South Georgia and North Florida can move from the digital catalog to the showrooms in Fernandina Beach, FL. Before comparing payment amounts, read furniture product descriptions carefully so the quote reflects the intended size, upholstery, and configuration.
The essential questions are simple: How many payments, on what dates, and what is the total paid?
Eligibility and Approval Limits Before You Apply
Approval isn't proof of affordability. A provider's decision answers whether it will extend credit under its criteria, not whether the payments will leave enough for groceries, housing, and an unexpected repair.
The Consumer Financial Protection Bureau's findings on BNPL borrowers found that 18% had a reported delinquency of at least 30 days on another open credit product, compared with 7% of non-borrowers. That association doesn't establish that BNPL caused the missed payments, but it makes household affordability an important separate check.
The CFPB also reported that many BNPL loans historically weren't furnished to nationwide credit-reporting companies. A provider may therefore assess an application without seeing every active installment commitment.
Prepare for the Credit Application
Application requirements can include payment history, existing credit, income information, and details about the funding account. Before submitting, confirm whether the application involves a soft or hard credit inquiry and what documentation is needed.
For help organizing application information, Fintrack's credit application guide offers a useful preparation resource. Mattress shoppers can also review financing considerations when credit is a concern before choosing an application route.
Affordability check: The useful limit is the amount remaining after essential bills and a savings cushion, not the maximum amount approved.
If the proposed payment would stretch that remainder, compare a smaller sectional configuration, a larger deposit from available purchase funds, or conventional financing. A longer agreement may reduce the monthly obligation, but its total cost still needs review.
A decline isn't a judgment of personal worth. The next step is to understand the stated reason and reconsider the purchase after obligations or circumstances change, rather than submitting repeated applications without a plan.
How a Pay-in-Four Plan Works From Checkout to Final Payment
A pay-in-four purchase should end with a saved agreement and a complete payment schedule. The smaller checkout figure is only part of the commitment, so the household needs the full sequence before accepting.

Follow the Checkout Sequence
Confirm the furniture and final order total. Select the piece, upholstery, and delivery arrangements before choosing financing, then check the amount being financed. A common slip is using the product-page price rather than the completed checkout total.
Read the complete repayment schedule. Review every installment, any disclosed charges, and the total amount paid. The first payment isn't the purchase price, and a small installment doesn't establish that the overall order is affordable.
Verify withdrawal dates and the funding account. Check which account will fund automatic payments and compare each debit with expected income. A payment landing just before payday can be difficult even when the month's income appears sufficient.
Complete the identity and approval process. Read the credit-inquiry disclosure before authorizing the check, and confirm that the approved terms match the offer being considered. Don't assume that every financing application uses the same kind of inquiry.
Save the agreement and enter the dates. Keep the accepted terms, order confirmation, and repayment schedule together, then add advance reminders to a calendar. Relying only on an email notification can leave too little time to correct a funding problem.
Verify the first debit and the remaining schedule. Confirm that the transaction cleared, then check the next withdrawal against the next paycheck and other bills. A pending transaction isn't the same as a completed payment.
Keep the Order and Payment Records Together
An in-store associate can help review the order details while the shopper reads the provider's schedule. Online applicants should save their account access and agreement so the financing records remain available if shopping continues in the showroom.
The CFPB's review of BNPL market trends and consumer impacts identifies mandatory autopay and uneven disclosures as potential consumer harms. The practical response is to check the withdrawal instructions rather than assume that automatic means effortless.
A clean start means the first debit clears on time and the next date is confirmed. A clean first month means every payment due that month has cleared, even if the schedule includes more than the initial debit.
Fees, Late Payments and Credit Reporting to Check First
Charges and credit effects to check before accepting a plan
| Charge | When it applies | What to confirm |
|---|---|---|
| Late payment fee | An installment is paid after its due date | Exact fee, any grace period, and whether fees can repeat |
| Failed payment fee | An autopay debit is declined, if the agreement provides for a charge | Provider's fee, retry policy, and the bank's overdraft or NSF terms |
| Payment-date change fee | A scheduled due date is moved, if the provider charges for changes | Whether changes are allowed, their cost, and the new confirmed date |
| Credit reporting | Payment activity is furnished to a credit bureau | Whether reporting goes to Equifax, Experian, or TransUnion and how late payments are handled |
Zero interest doesn't necessarily mean zero cost. The Federal Trade Commission's consumer guidance warns that BNPL plans may charge for individual payments, late payments, or changing a payment date, and that reported late payments can harm credit history.
Separate Provider Charges From Bank Charges
A late fee concerns the installment deadline. Say a payment is due before a paycheck arrives: paying after payday could still count as late under the agreement, even if the delay feels brief.
A failed debit creates a different question. The provider may retry the withdrawal, while the bank may apply its own overdraft or insufficient-funds terms; the shopper needs to understand both sides rather than looking only for a provider's late fee.
Moving the date isn't automatically a free solution. Before relying on an adjustment, confirm that the change was accepted and that the account now displays the revised schedule.
An interest-free label describes interest, not every possible charge.
Check Reporting Before a Problem Occurs
Credit reporting isn't itself a fee, but its consequences belong in the same comparison. A shopper shouldn't assume that making timely payments will build credit, or that a missed payment will remain invisible.
In the Federal Reserve's 2023 household survey, 18% of BNPL users reported making a late payment, and 11% of all BNPL users said they were charged an additional late-payment amount. Those findings make payment timing a practical concern, not just fine print.
Before acceptance, read the fee schedule, reporting policy, and autopay authorization. Record the disclosed fee amounts beside the payment dates, including whether a date change costs anything and whether a failed debit will be retried.
That written record allows a fair comparison: scheduled payments plus interest and disclosed charges, with a separate note for potential bank costs. The most attractive headline isn't always the most suitable agreement.
Which Financing Option Fits Each Furniture Purchase
Financing option by furniture purchase type
| Purchase | Option to compare first | Check before signing |
|---|---|---|
| Accent chair or ottoman | Pay-in-four, if ready to deliver | Each debit date fits payday |
| Recliner or lift chair | Pay-in-four or short installment plan | Total paid including any fees |
| Sectional or sleeper sofa | Longer installment plan or conventional financing | Monthly total alongside other open plans |
| Mattress or storage bed | Installment plan after the Mattress Guide review | Eligibility, deadlines, exclusions, and costs for returns or exchanges |
| Custom-order sofa or dining set | Financing with a schedule reviewed against delivery timing | Refund treatment if production or delivery is delayed |
| Clearance piece | Pay in full at up to 70% off | Whether the available cash price makes financing unnecessary |
The table identifies options to compare, not automatic recommendations or promises of approval. A purchase works financially only when its payment timing suits the household.
Match the Plan to the Actual Order
An accent chair for a reading corner may suit a short repayment schedule if it's ready to deliver and the cash is already allocated. Adding an ottoman changes the financed total, so both pieces should be included before accepting terms.
For a recliner or lift chair, La-Z-Boy and Stressless offer starting points for a comfort-focused showroom visit. Testing seat support and operation before financing helps avoid choosing by installment size alone.
A Lexington or Hooker Furniture sectional, loveseat, or sleeper sofa calls for careful configuration decisions. Seat count, room access, and sleeping needs should be settled before comparing longer repayment agreements.
Mattress shoppers can use the Mattress Guide to narrow comfort and support choices. Storage beds with drawers beneath the mattress are available in different styles and finishes, so the chosen bed and mattress combination should be priced as a complete order.
Use Design Guidance Before Borrowing
- Custom-order packages: A personalized sofa or dining set needs a written order specification and a repayment schedule reviewed against expected production and delivery.
- Clearance pieces: Lott's Furniture offers savings of up to 70% off in its Clearance section. Paying in full may be the value-focused choice when it preserves enough cash for essential expenses.
- Room planning: The Style Quizzes and in-store associates can help narrow dimensions, fabric choices, and coordinating pieces before an application.
Furniture is a high-consideration purchase, particularly when the goal is an investment-quality room rather than a temporary arrangement. Resolving the design decisions first helps keep financing attached to a deliberate purchase.
The rule of thumb is a monthly amount the household can comfortably pay, not the largest order an approval will support.
Custom Orders, Delivery Delays and Returns on a Plan
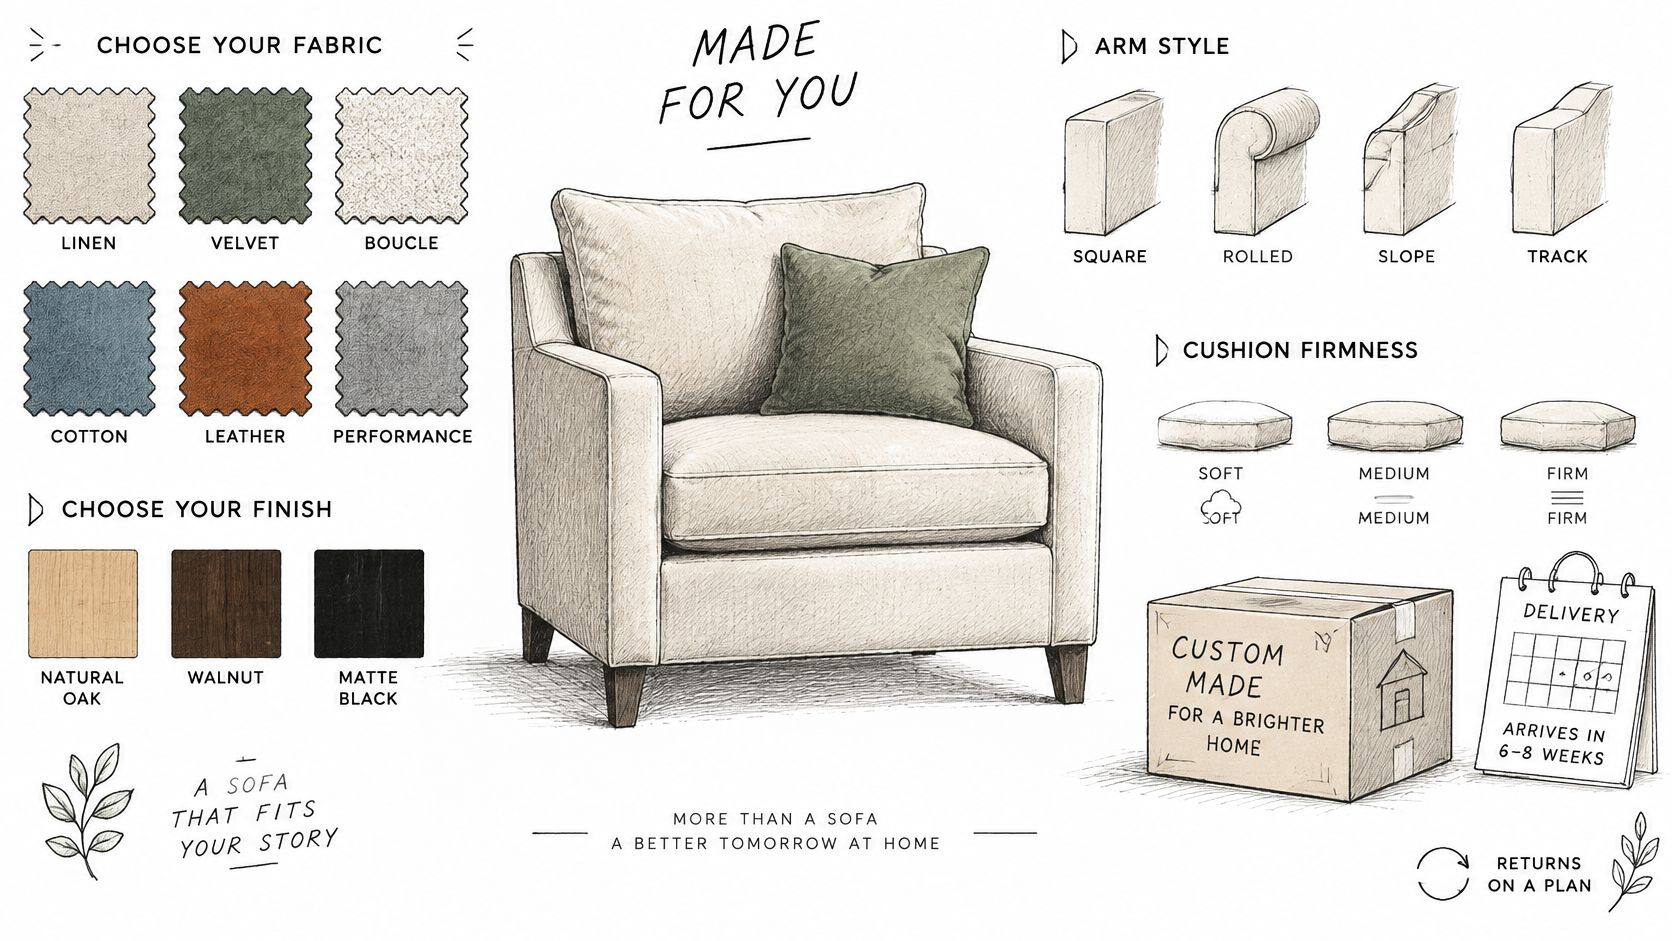
A custom order combines personal design decisions with a separate financing agreement. The Special Order Program allows customers to tailor furniture to their style, comfort, and spending plan, and most vendors support personalized designs through choices such as fabrics, finishes, comfort levels, and arm styles.
Keep Delivery and Financing Questions Separate
Production may extend beyond the first installment cycle. Before signing, review the custom-order process and establish whether payments begin at purchase, shipment, delivery, or another event specified in the agreement.
The CFPB's report on consumer use of BNPL and other unsecured debt provides context for understanding BNPL alongside other obligations. For a made-to-order purchase, the useful safeguard is a clear record connecting the order, its financing, and any later adjustment.
If an item arrives damaged, incomplete, or different from the order:
- Document the condition. Take dated photographs at delivery, including the affected area and the complete piece.
- Contact Lott's Furniture first in writing. Describe the concern and identify the order so the issue can be reviewed against the purchase record.
- Preserve the paperwork. Keep the specification, agreement, delivery documents, and payment history together.
- Get payment instructions in writing. Confirm the provider's dispute and refund procedure, including whether payments are paused or must continue.
- Monitor the actual balance. Don't treat a promised refund as a completed account adjustment.
Understand the White-Glove Delivery Standard
Every piece undergoes a rigorous multi-point inspection before reaching the customer. White-glove, in-home delivery includes placing the furniture exactly where the customer wants it, rather than leaving a box at the door.
For daily-use pieces, Smith Brothers performance-fabric options and Hooker Furniture selections can be considered alongside care needs and household routines. Inspection and careful placement support the delivery experience, while written records support a clear response if a concern remains.
Neither a delayed delivery nor a return request should lead to an improvised payment decision. The account needs documented instructions until the provider formally updates the obligation.
Confirm Your Repayment Plan Before You Check Out
Start with a repayment calendar that includes every active plan, not just the new furniture purchase. Record each withdrawal separately, then total the payments due in each month.
| Calendar entry | Information to record |
|---|---|
| Each active plan | Purchase, remaining balance, monthly obligation, and total scheduled cost |
| Each withdrawal | Exact date, amount, and funding account |
| Essential bills | Rent or mortgage, utilities, food, transport, and insurance |
| Savings | Emergency savings contribution and a protected cash cushion |
| Available income | Expected deposit dates and amounts |
The CFPB's BNPL market report examines issues including loan stacking, persistent use, and obligations that ordinary credit records haven't always captured well. A consolidated calendar addresses that visibility problem at the household level.
Test the Busiest Payment Period
Say a sofa is financed first, a mattress follows, and accessories are added later. Each application may look manageable on its own, but the decision should rest on the combined obligation during the period when all remain active.
The calendar needs to answer both questions: What is the total furniture payment burden, and what remains for rent, utilities, and emergency savings? If a month becomes uncomfortable, reduce the order, postpone a nonessential piece, or compare a different repayment structure before signing.
Protect the essentials: A payment plan should fit around housing and necessary bills, not require those bills to move.
Bring the Calendar Into the Shopping Decision
A Fernandina Beach, FL showroom visit allows shoppers to test a sofa or recliner with an associate after browsing the digital catalog. An online style consultation can begin with the Style Quizzes, while mattress browsing can be narrowed by size, comfort, type, and brand with help from the Mattress Guide.
Delivery planning belongs in the same conversation. Reviewing the white-glove delivery service helps connect the room plan with convenient in-home placement.
For product questions, the Service Request page in Customer Tools or a text to the business connects shoppers with support staff, who respond as soon as possible. The email list also provides new arrivals and special offers without requiring an immediate purchase.
Book a showroom visit or online style consultation and bring the completed calendar. The most useful conversation begins with a comfortable payment boundary and a clear picture of the room.
Frequently Asked Questions About Buy Now Pay Later Furniture
Does Paying Off a Plan Early Cost Anything?
Some pay-in-four agreements allow early payoff without a charge, but the signed prepayment terms control. Before sending an additional payment, confirm how it will be applied and whether scheduled automatic withdrawals will change.
What Happens if a Sofa Is Returned While Payments Remain?
Request written confirmation of the accepted return, refund amount, and account adjustment. Scheduled payments should continue unless the provider confirms a pause or different instructions, and the account should be monitored until the credit appears.
Will a BNPL Plan Change a Credit Score?
It can, depending on the application inquiry and the provider's reporting policy. Confirm whether activity is reported to Equifax, Experian, or TransUnion rather than assuming either a credit-building benefit or no credit effect.
Can a Furniture Order Be Split Across Separate Plans?
Only if the retailer's checkout process and each provider permit the arrangement. Separate agreements create separate obligations, so both belong on the repayment calendar before either is accepted.
Is a Showroom Visit Required to Apply?
Online financing tools allow the process to begin without a showroom visit, subject to the available offer's application requirements. A shopper can start with online style guidance and finish design decisions in store, while retaining the relevant order and financing records.
Lott's Furniture offers furniture and mattresses, personalized special orders, financing options, and inspected white-glove, in-home delivery for South Georgia and North Florida. Visit Lott's Furniture to arrange a Fernandina Beach showroom visit or online style consultation, and bring a repayment calendar so the purchase can be considered alongside the household's real monthly commitments.